When siblings inherit a home together, the house is rarely the hardest part. How to communicate, evaluate the property, and choose between selling, a buyout, or co-owning.
Inheriting a home with brothers or sisters can turn stressful fast. One wants to sell, one wants to keep it, one lives far away, and everyone is grieving. This video walks through a plan for communicating, evaluating the property, and choosing a path while keeping the family relationship intact.
1. Communicate first
Before discussing outcomes, agree on the process: who will gather information, how often you will talk, and how a decision will be made. Families who settle the process first argue less about the result.
2. Evaluate the property together
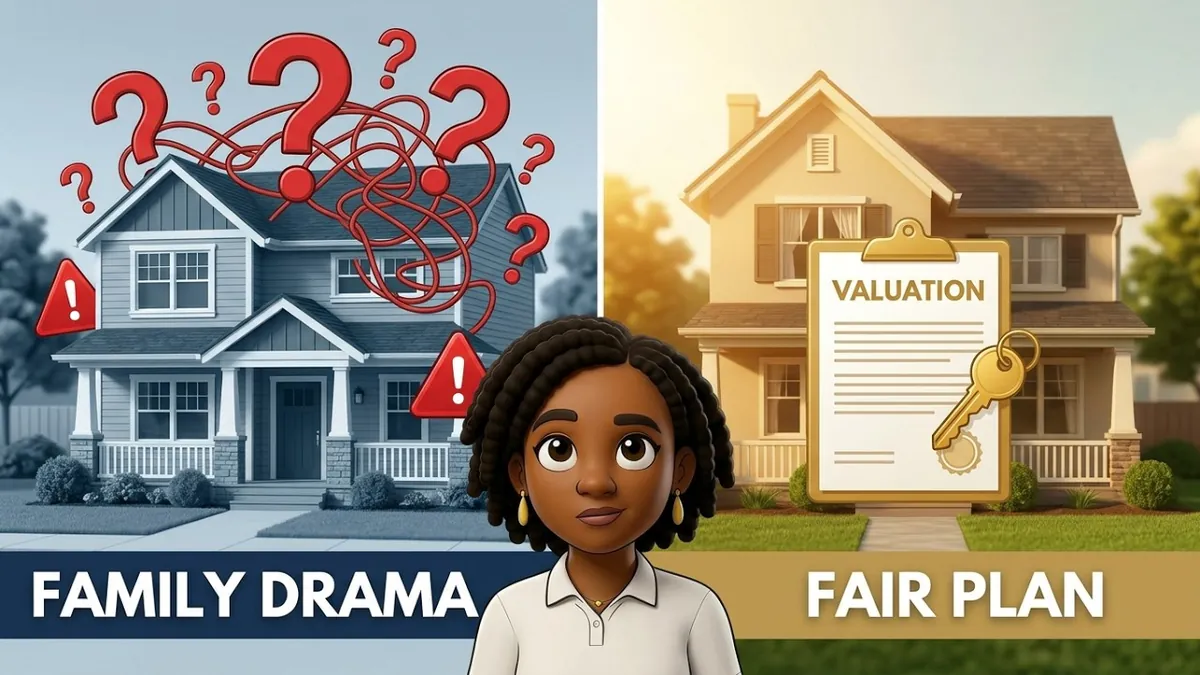
Disagreements often come from different assumptions about the house. Use one shared set of facts: its condition, what it might sell for, what it costs to hold each month, and what repairs it needs. An independent valuation can help everyone start from the same number.
3. Choose a path
- Sell: proceeds are divided among the heirs, either after a listing or through a direct, as-is sale.
- Buyout: one sibling buys out the others’ shares, usually based on an agreed value.
- Co-own: the siblings keep the house together, with a written agreement on costs, use, and an eventual exit.
A neutral voice can help
Sometimes the same information lands better from someone outside the family. We help siblings compare selling, a buyout, and keeping the house side by side, and we can coordinate the cleanout and sale if that is the direction everyone chooses.